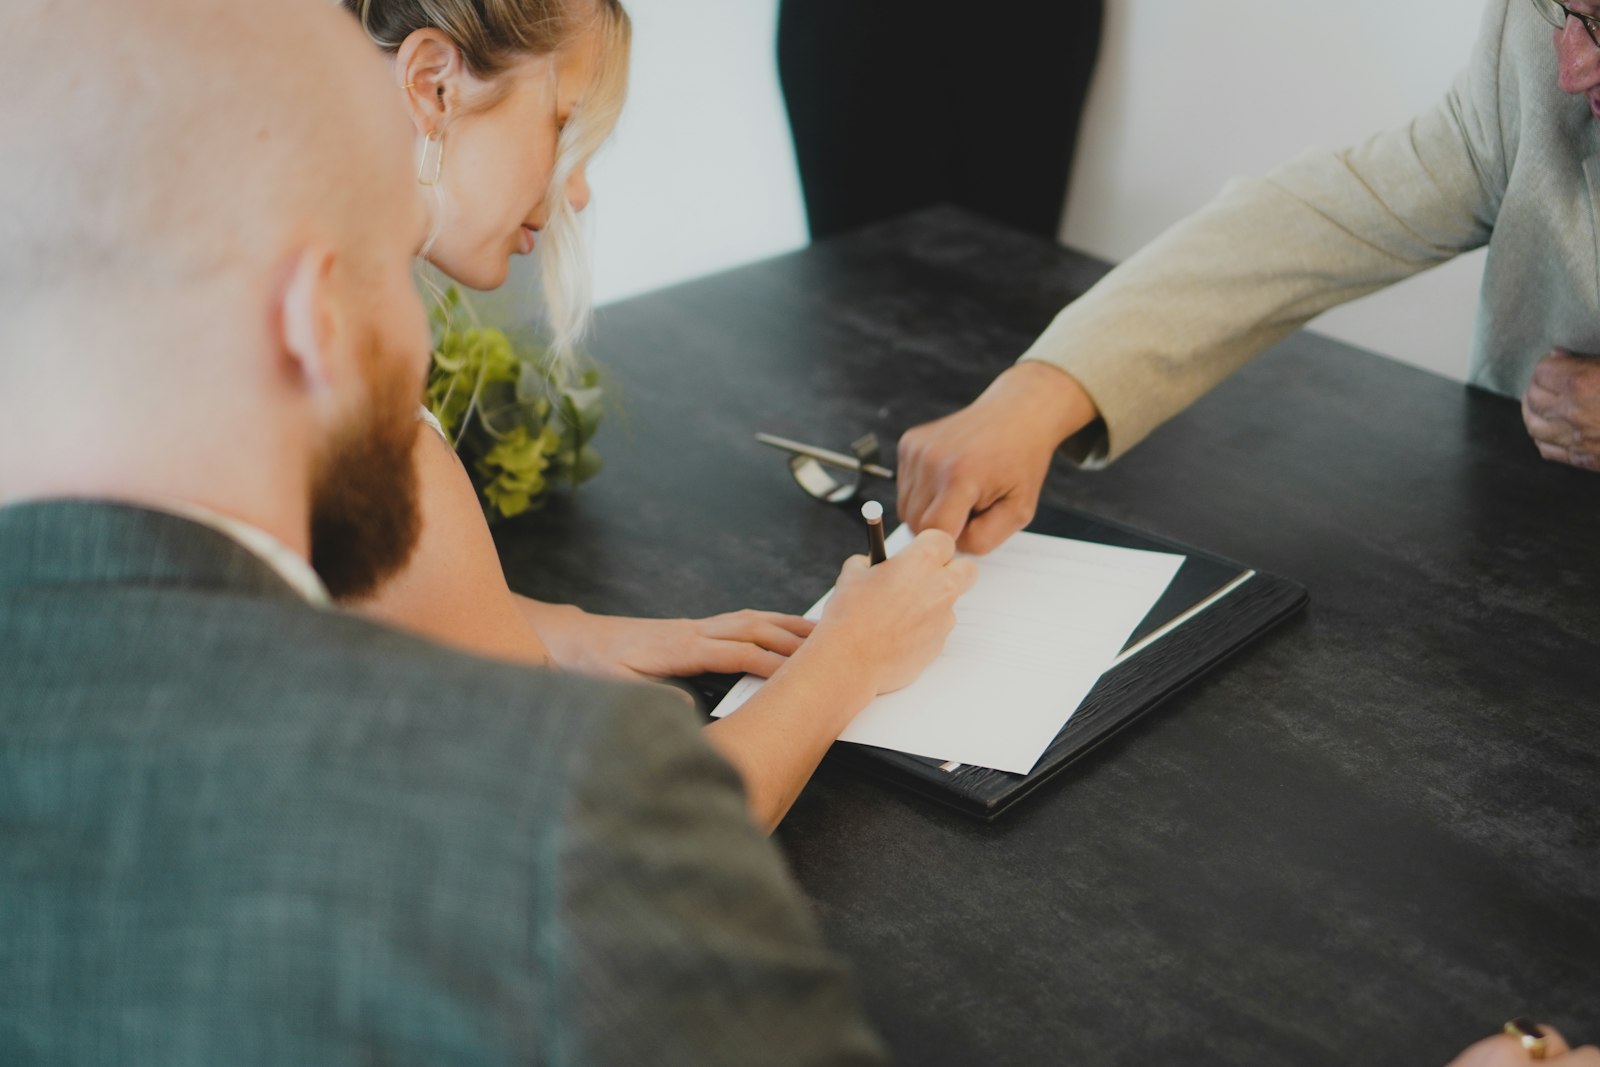
Every week the same questions about the notaire come up in our Facebook group. Who chooses them? Do I need to speak French? Why do they want to know how I am married? And almost always the questions come too late, when the signing date is already set.
Below is what a French notaire does, what they don’t do, and what you need to arrange before you sit down at that table. Starting with the point most British and Irish buyers miss: you can bring your own notaire, and it costs you nothing extra.
One notaire instead of two solicitors
In the UK or Ireland, buyer and seller each have their own solicitor or conveyancer. In France there is one official at the centre of every sale: the notaire. A notaire is a public officer. They are compulsory for every property sale and they make the deed official. Important to understand: they serve the transaction, not you. They check that the sale is legally sound, that the seller really owns the house, that there is no mortgage or right of way you don’t know about, and they collect the taxes for the state.
What a notaire is not:
- Not your solicitor. They don’t negotiate for you and don’t advise you on the price.
- Not a surveyor. What is technically wrong with the house is not their job. Part of that is in the survey pack (diagnostics), and nowhere else.
- Not an estate agent, although French notaires do sell houses too. immobilier.notaires.fr has listings you often won’t find anywhere else, and our Search Helper includes it.
They are, however, the person who sees everything: the land registry, the planning permissions, rights of way, pending disputes. So the quality of your purchase depends a lot on whether you ask the right questions.
You can have your own notaire, at no extra cost
This is the best-kept secret of buying in France.
Usually buyer and seller use the same notaire, often the seller’s or the agent’s. That is allowed, but it isn’t compulsory. You can appoint your own notaire, wherever they are in France. The two notaires draw up the deed together and share the fee between them. The total fees stay exactly the same. It costs you nothing to have someone at the table who looks only at your interests.
For a British or Irish buyer that is extra useful: you can choose a notaire who speaks good English, even if they are 400 kilometres away, while the local office handles the sale as usual.
How to arrange it: when you sign the compromis, say that you want to appoint a deuxième notaire and pass on their details. It is a completely normal request. Do it in good time; adding one later is possible but causes delays.
No French? Then a translator comes along
The deed is drawn up in French and read out. The notaire must be able to establish that you understand what you are signing, otherwise the deed can be challenged later. If your French isn’t good enough, they will bring in a sworn translator (traducteur-interprète assermenté) for the signing.
- Expect a few hundred euros, usually paid by the buyer. Your notaire normally knows one. Ask about it yourself rather than waiting.
- A relative who “speaks good French” is not a sworn translator and is often not accepted.
- Can’t be there in person? You can sign by power of attorney (procuration). It has to be translated and signed in advance, so it moves the work forward rather than making it disappear.
Don’t skip this to save money. A deed you can later be said not to have understood is the last thing you want.
The papers you need to provide
The notaire asks for ID, proof of address and documents about your civil status: birth certificate, and marriage certificate or divorce papers if relevant. They also have to ask where your money comes from. That is European anti-money-laundering law, not mistrust: if the money comes from a sale, an inheritance or a gift, make sure you can show it.
UK and Irish documents are not treated the same. Since Brexit, UK certificates are documents from outside the EU. Expect the notaire to ask for a sworn French translation, and sometimes an apostille from the FCDO. Irish documents fall under the EU rules on public documents, which can make things simpler: ask the registrar for a multilingual standard form. Either way, ask your notaire early exactly what they want. In practice this causes more delays than the deed itself.
Paying from a UK account? The money goes to the notaire’s client account, not to the seller or the agent. Converting pounds to euros through a currency specialist is usually cheaper than through your bank, and lets you fix a rate in advance. Allow time for the transfer to arrive before the signing date.
How you are married matters
A French notaire wants to know your matrimonial regime before drawing up the deed. It determines how you own the house and what happens when one of you dies. That is a question British buyers are rarely asked at home: English, Welsh and Scottish law have no matrimonial regime in the French sense. The notaire will work out which law applies to your marriage, which can depend on when and where you married and where you first lived together. Bring your marriage certificate and raise it early.
Then there is the question of how you buy the house together. The usual options:
- En indivision. Each owns a share, usually 50/50. The standard and the simplest.
- Clause de tontine (also clause d’accroissement). When one dies, the whole house goes to the survivor, as if they had always owned it alone. Sounds attractive, but it is not always favourable for tax or legally, and it is hard to undo.
- Through an SCI, a French property company. Popular for shared ownership and letting, but it comes with bookkeeping and obligations.
This is a choice you make once and that only does its work years later. Discuss it with your notaire beforehand, not on the day of the deed.
Inheritance, briefly and honestly
France has réserve héréditaire: children are guaranteed a share of the estate and cannot simply be disinherited. The EU Succession Regulation, which France applies to everyone including UK nationals, lets you choose in your will the law of your nationality, for example English law.
Don’t count on that too much. In 2021 France added a rule that in some cases lets children still claim their French share from assets located in France. That rule is legally disputed. On top of that come inheritance tax in France and possibly in the UK or Ireland.
What you should do is not work this out yourself, but put it on the table with your notaire as soon as you have a house in mind. Especially with blended families, children from an earlier relationship, or if you already have a will at home.
The buying process, step by step
In France this usually happens in writing, through the agent. There is no gazumping culture as in England: once the compromis is signed, the seller is bound.
This is where you set the conditions (clauses suspensives): mortgage, planning, results of checks. Anything you don’t put in here, you can’t rely on later.
As the buyer, you can withdraw within ten days of receiving the signed compromis, without a reason and without cost. The seller does not have that right.
Paid into the notaire’s client account. Not to the seller and not to the agent.
The notaire does the searches, requests documents from the town hall and checks pre-emption rights.
Reading, signing, keys. The balance is already in the notaire’s account by then.
What does the notaire really cost?
What is called “notaire fees” (frais de notaire) is mostly not for the notaire at all. On an existing house it is about 7 to 8.5 percent of the price, and the lion’s share is transfer tax the notaire collects for the state, comparable to stamp duty. The notaire’s own fee (émoluments) is fixed by law and a small part of the total. On a new build the whole thing is much lower, around 2.5 percent.
Work out your own situation with the buying costs calculator, including agency fees and the yearly running costs.
Seven questions to ask your notaire
- Can I appoint my own notaire, and what does that mean for the timing?
- Which clauses suspensives are in my compromis, and which am I missing?
- Is there a pre-emption right (droit de préemption) for the town or the SAFER?
- Are all outbuildings, the pool and any extension covered by planning permission?
- Which rights of way and easements are there on the land: access, water pipes, hunting rights?
- Under which matrimonial regime am I buying, and how do we set up the ownership?
- What happens to this house when I die, given my family situation?
Tools for this page
Want the complete buying guide?
The step-by-step plan for buying a house in France, as a PDF in your inbox.
We email you the guide. Unsubscribe at any time.
General information, not legal or tax advice. Rules change; check your own situation with your notaire. Updated: October 2026.
Photo: Annika Wischnewsky on Unsplash